Senior Living Insurance Brief, Week of November 2, 2026
Senior living insurance continues to move in two different directions.
The latest Q3 commercial insurance data show property pricing continuing to soften, while liability and umbrella remain under pressure.
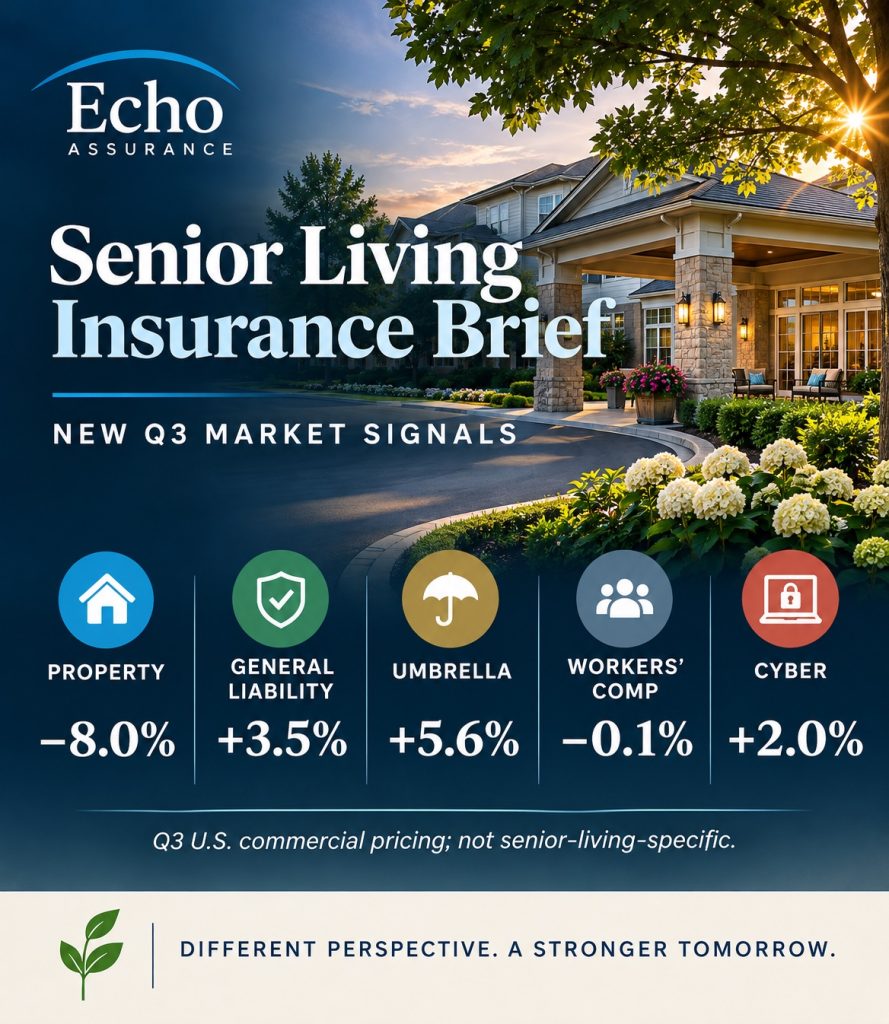
Property rates declined 8.0%. General liability increased 3.5%. Umbrella increased 5.6%. Workers’ compensation was essentially flat, and cyber increased 2.0%.
These are broad U.S. commercial market results, not senior living-specific renewal outcomes, but the implications for operators are clear.
Property remains the best opportunity to improve pricing and structure. That means operators should be challenging deductibles, sublimits, valuation assumptions, business interruption protection, and other terms rather than simply accepting a lower renewal premium.
Liability is different. Professional liability, general liability, and umbrella continue to reflect concern around severity, staffing, resident care, documentation, venue, and claims history.
Workers’ compensation remains comparatively stable, but individual results will still depend heavily on state, experience modification, injury trends, and return-to-work performance.
The practical takeaway:
A softer property market does not mean the entire insurance market is soft.
Senior living operators should be looking at each coverage line separately and asking where the market is rewarding them, where insurers still perceive elevated risk, and what evidence they can provide to improve that perception.
The operators who can best demonstrate the quality of their risk should be in the strongest position to benefit.
Data: Q3 U.S. commercial insurance pricing. Figures reflect broad commercial market results, not senior living-specific renewal outcomes.